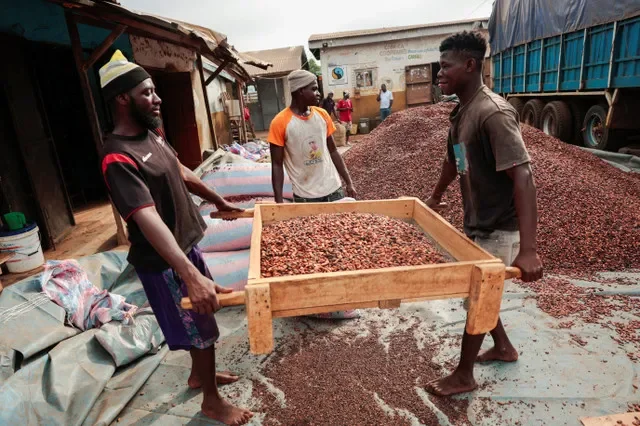
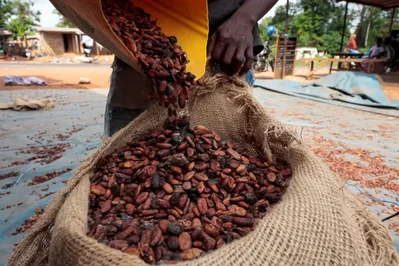
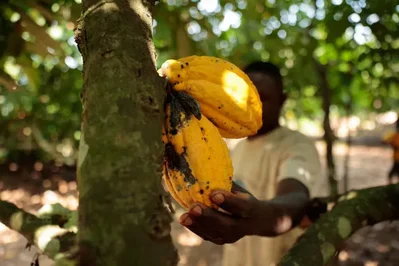
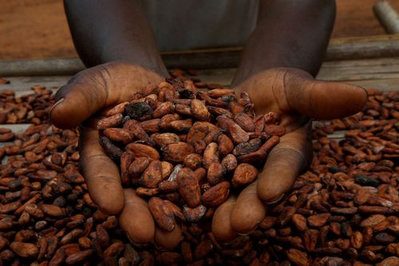
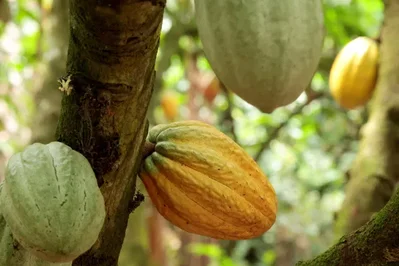
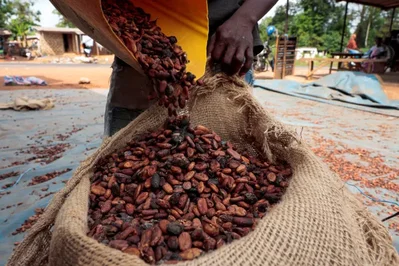
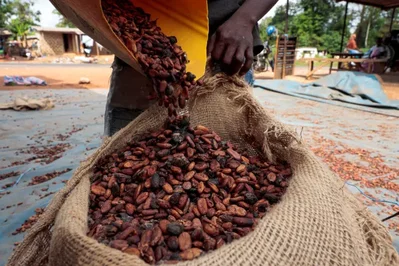
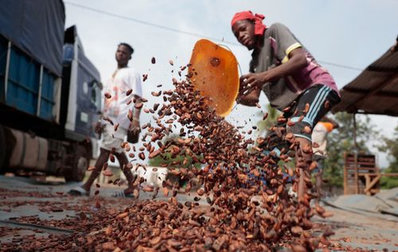
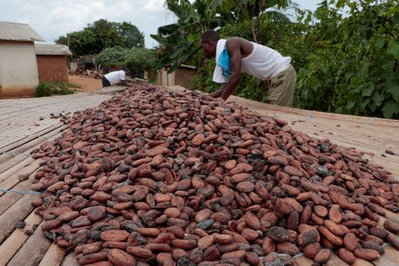
Ivory Coast is exploring a reform of its Cocoa (commodity) marketing system to better align government-mandated farmer prices with international market trends. The move follows a sharp decline in global prices that has triggered a sales crisis and left a significant surplus of beans across the West African nation.
After surging to record highs in 2024, world cocoa futures have since lost three-quarters of their value, currently trading at approximately $3,300 per ton. This volatility created a disparity between the fixed prices set for Ivorian farmers last October and the lower global market rates, prompting international traders to halt purchases. In response, the government has stepped in with a pledge of more than 500 billion CFA francs ($892.06 million) to buy back unsold stocks and provide liquidity to producers.