Energy Supply Concerns Weigh on Indian Rupee and Bonds
The rupee and bonds face strain as the Iran war disrupts energy supplies. The central bank is intervening as oil prices remain above 100 dollars per barrel.

Financial markets in India are bracing for a period of sustained volatility as the ongoing conflict involving Iran disrupts global energy supplies and dampens investor appetite for emerging market assets. The Indian rupee recently touched a record low of 92.4750, a decline mitigated only by active intervention from the Reserve Bank of India (RBI). Global energy markets have reacted sharply to military developments, with Brent Crude Oil prices surging past $100 per barrel. Tensions have escalated as the United States dismissed diplomatic overtures from Middle Eastern allies, instead threatening further strikes on critical infrastructure such as the Kharg Island oil export hub. This geopolitical instability has fueled safe-haven demand for the dollar, which gained 1.6% last week. Analysts at The Goldman Sachs Group, Inc. highlighted the significant risks facing the Indian economy.
"India faces a material terms-of-trade shock from higher energy prices, with meaningful spillovers via trade, energy supply chains, and remittances."
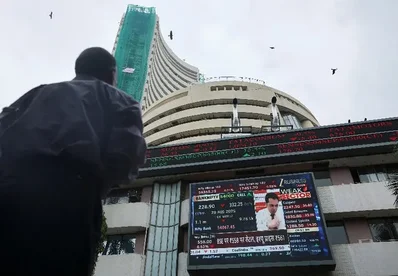
The firm has revised its 12-month forecast for the rupee to 95, down from a previous estimate of 94. While the RBI is expected to continue its efforts to curb excessive volatility, market participants believe the central bank may not defend specific price levels if oil remains elevated. Foreign portfolio outflows have added to the pressure, with overseas investors selling over $5.5 billion in local stocks so far in March.
Despite the external pressure, India's benchmark 10-year government bond yield ended Friday at 6.6798%. This stability is largely attributed to aggressive purchasing by the RBI, which net bought 572.10 billion rupees worth of bonds in the week ending March 6—the largest weekly purchase on record. Traders expect the 10-year yield to fluctuate between 6.62% and 6.72% this week, driven by central bank support and developments in the energy sector. Rajeev Radhakrishnan, CIO-fixed income at SBI Mutual Fund, noted that while the bond market remains anchored by central bank activity, swap markets are already hedging against potential risks.
"If current external dynamics worsen and fears of imported inflation increase, the RBI may need to reassess the extent of liquidity support being provided."
Market participants are now looking toward several key economic events scheduled for the coming week. In India, the February WPI inflation data is set for release on Monday, March 16, with a Reuters poll projecting a 2.00% increase. The U.S. economic calendar is also dense, featuring February industrial production on Monday, followed by PPI manufacturing and factory orders on Wednesday. The most significant event will be the Federal Reserve monetary policy decision on Wednesday, March 18, which will likely influence global sentiment alongside weekly jobless claims and new home sales data later in the week.