Silver Deficit to Widen in 2026 Amid Liquidity Risks
Silver faces a sixth year of deficit as stocks drop by 762 million ounces. Research warns of liquidity risks even as industrial demand is forecast to fall.

The global Silver market is entering its sixth consecutive year of structural deficit, with significant stock drawdowns raising the risk of a liquidity squeeze. Research released by the Silver Institute and consultancy Metals Focus indicates that 762 million troy ounces have been removed from global inventories since 2021. This persistent gap between supply and demand continues to shape market dynamics despite a recent cooling in overall demand expectations.
While prices have fallen approximately 35% from the record high of $121.6 an ounce seen in January, the market remains sensitive to supply constraints. The groundwork for the previous price surge was laid in 2025, driven by substantial metal inflows into the United States and silver-backed exchange-traded products (ETPs). These factors, combined with a spike in physical demand, led to a liquidity crunch in the United Kingdom benchmark market.
Metals Focus reports that liquidity has seen some improvement recently as metal flowed back from American inventories and ETPs experienced outflows. However, the buffer remains thin. Only 28% of the 884 million ounces held in London vaults at the end of March were not tied to ETPs, leaving a relatively small portion available to support market liquidity.
Conditions for a silver squeeze will be created again, requiring further outflows from the U.S., if the price becomes more volatile and Indian demand gets active, especially coupled with inflows to ETPs storing their metal in London.
Market analysts expect the global deficit to widen to 46.3 million ounces in 2026, up from 40.3 million in 2025. This comes despite a projected 2% drop in total demand, as industrial and jewellery consumption weakens. In particular, industrial fabrication is expected to fall 3% to a four-year low. Analysts warn that ongoing geopolitical tensions, including the impact of conflicts involving Iran, pose a threat to global economic growth and could further dampen industrial silver use.
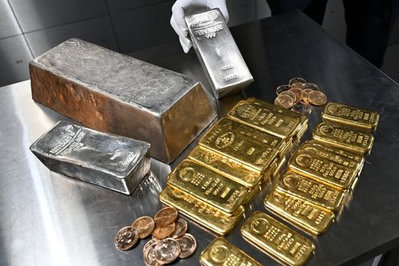
Conversely, demand for coins and bars is expected to rise by 18%, supported by a recovery in buying within the American market. Demand from India remains a critical variable; while it has eased recently, a resurgence could quickly tighten the market again.
Supply and Demand Outlook for 2026:
- Total Supply: 1,066.4 million ounces
- Mine Production: 844.1 million ounces
- Recycling: 211.3 million ounces
- Net Hedging Supply: 10.0 million ounces
- Official Sector Sales: 1.0 million ounces
Demand Forecast for 2026:
- Total Demand: 1,112.6 million ounces
- Industrial Fabrication: 639.6 million ounces
- Photovoltaics: 151.0 million ounces
- Jewellery: 159.4 million ounces
- Silverware: 33.5 million ounces
- Coins and Bars: 257.6 million ounces
The resulting market balance for 2026 is a deficit of 46.3 million ounces. When accounting for projected ETP investment of 30.0 million ounces, the adjusted market balance falls to a deficit of 76.3 million ounces.