United Airlines Projects Lower Profits Amid Fuel Surge
United forecast lower profits as fuel costs squeeze margins despite strong premium demand. The carrier beat first-quarter estimates with a 10.6% revenue rise.

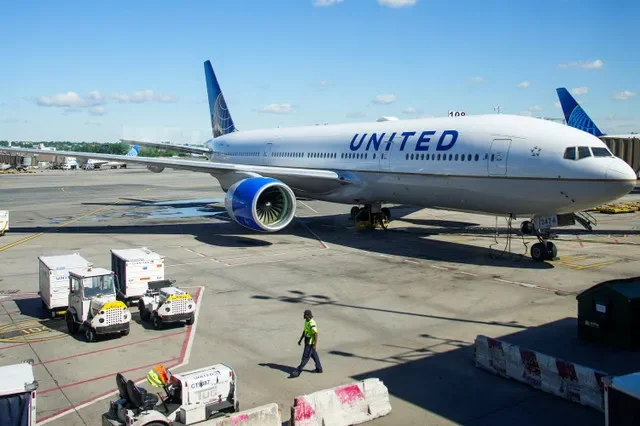
UNITED AIRLINES HOLDINGS INC has issued a cautious financial outlook for the second quarter and the full year, projecting profits that fall short of Wall Street expectations. The carrier attributed this forecast to a sharp rise in jet fuel prices linked to the conflict in Iran, which has pressured margins despite a continued surge in demand for premium travel services.
The airline's stock performance turned positive in after-hours trading following an initial decline, as market sentiment improved on news that the United States extended a ceasefire in the region. This geopolitical shift raised expectations for a potential cooling of energy prices, which have impacted global benchmarks including Brent Crude Oil and West Texas Oil. Analysts at Jefferies noted that while fuel costs are the primary headwind, the airline's underlying operational performance remains consistent with previous trends.
The fuel price volatility is currently reshaping the financial landscape for several major carriers. DELTA AIR LINES INC has already adjusted its growth plans, and ALASKA AIR GROUP INC recently withdrew its full-year guidance, noting that fare increases have only partially offset the rising cost of fuel. United expects to pay an average of $4.30 per gallon for jet fuel in the current quarter, leading to a projected adjusted profit of $1 to $2 per share. This midpoint of $1.50 is significantly lower than the $2.08 per share anticipated by analysts.
United indicated that it expects to recover between 40% and 50% of its increased fuel costs through higher fares during the second quarter. The airline anticipates this recovery rate will climb to 80% or higher by the end of the year. In response to the tighter margins, the company is adopting a more disciplined approach to capacity, with growth expected to remain flat or increase by no more than 2% in the second half of the year.
Despite the fuel-related challenges, United's first-quarter performance surpassed market expectations. The airline reported adjusted earnings of $1.19 per share on revenue of $14.6 billion, representing a 10.6% increase from the previous year. Growth was particularly strong in the high-margin segments, with premium revenue and corporate revenue both rising by 14%, while loyalty revenue increased by 13%. These gains occurred even as the company's total fuel expenditure rose by 12.6% year-on-year.