Traders Bet Middle East Oil Supply Shock Is Temporary
Traders view the Middle East conflict as a temporary supply shock. Data shows a surge in near-term volatility while long-term oil prices remain largely stable.

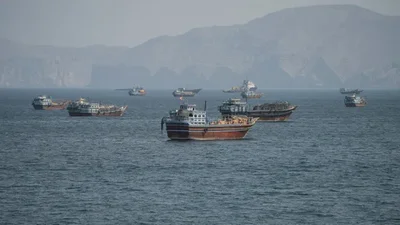
Oil options and futures markets are signaling that the current geopolitical tensions in the Middle East may be a temporary phenomenon. Traders are increasingly positioning themselves in financial structures designed to profit from a price retreat following the initial surge. This trend suggests that the market views the recent supply shock as a logistical hurdle rather than a long-term structural shift. The recent military actions involving Israel and the United States against Iran have triggered significant volatility. War-risk insurance premiums have climbed, freight rates have reached record levels, and logistical bottlenecks at the Strait of Hormuz have disrupted global oil flows. Despite these pressures, derivative data indicates a belief that the crisis will be short-lived. Market analysts are closely monitoring the divergence between short-term and long-term expectations. Brian E. Kinsella, a former energy specialist at Goldman Sachs, noted that the current situation reflects a specific type of market stress. > What we’re watching in real time is the difference between a logistics crisis and a structural one. Kinsella further observed that current sentiment leans toward a temporary disruption. > The market is betting it’s logistical and I think that is the right read. Data from the Brent Crude Oil market supports this outlook. While the 30-day at-the-money implied volatility for Brent jumped 17.5 points to 68% recently, the 60-day and 90-day tenors saw much smaller increases of 5.9 and 2.8 percentage points, respectively. This concentration of volatility at the front end of the curve suggests that traders expect the most intense price swings to occur in the immediate future. The futures curve for Brent is exhibiting its steepest backwardation since the conflict between Russia and Ukraine in 2022. The spread between the front-month contract and the six-month contract has widened to approximately $10, signaling tight near-term supply while implying that long-term availability remains stable. On the West Texas Intermediate (WTI) front, the put-to-call ratio experienced a sharp decline to 0.35 on Monday before rebounding to 0.56 on Tuesday. This movement reflects a surge in bullish call buying followed by a return to downside protection. Rebecca Babin, a senior energy trader at CIBC Private Wealth US, pointed out that dealers are currently holding significant short positions on deep out-of-the-money calls, creating a more negative gamma profile. Babin also highlighted that much of the 2027 Brent strip is still trading below $70 a barrel. > Producers have also used the rally to hedge forward output, creating natural selling pressure on longer-dated volatility. This hedging activity by producers reinforces the narrative that the price spike is not expected to persist indefinitely. Darrell E. Fletcher, managing director at Bannockburn Capital Markets, echoed this sentiment regarding the futures curve. > Risk premiums remain concentrated at the front of the futures curve, reinforcing the view that traders still see the disruption as temporary. Open interest data provides further evidence of a tactical shift rather than a structural repricing. Brent options open interest saw a dramatic decline in late February, falling from 388,000 contracts to about 73,000, before rebounding to over 700,000 contracts in early March. This pattern suggests that traders rapidly unwound previous positions to establish new hedges as the conflict unfolded.