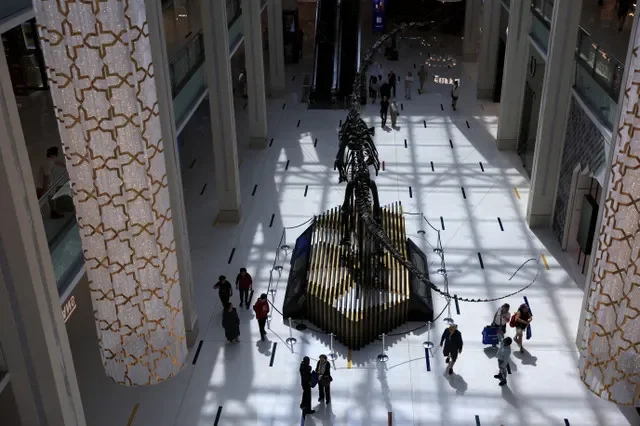
The Middle East represents a vital pillar for the industry, accounting for approximately 5% to 6% of global luxury sales. According to data from Morgan Stanley and Bank of America, the United Arab Emirates generates nearly half of this regional revenue, with the majority of transactions occurring in Dubai. The market relies heavily on high-spending tourists from Russia, Saudi Arabia, China, and India.
As of early March, retail activity has slowed to a crawl. Many flagship stores in major shopping hubs remain shuttered or are operating with skeleton crews. This disruption comes at a sensitive time for investors who had viewed the Middle East as a rare growth engine while recovery in China remains sluggish and potential tariff risks loom in the West. Analysts at Morgan Stanley have warned that the conflict could also derail the \"Ramadan rush,\" a period when affluent residents from the Gulf typically travel to Europe for luxury shopping excursions.
Exposure to the regional volatility varies significantly across major fashion houses. CIE FINANCIERE RICHEMONT SA, the owner of Cartier, and Italy-based ERMENEGILDO ZEGNA NV are among the most vulnerable, with both groups deriving roughly 9% of their total sales from the Middle East. In contrast, BURBERRY GROUP PLC is considered to be among the least exposed to the current regional downturn.
The financial impact has been immediate on public markets. The STOXX Europe Luxury 10 Index recorded a decline of approximately 9% over a two-day period, marking its most severe short-term drop since the tariff-related volatility seen in April. This market reaction underscores the fragility of the luxury sector as it navigates geopolitical instability alongside broader economic headwinds.