Indian Rupee Gains as Oil Prices Fall and RBI Intervenes
The rupee rose 0.57% to 91.8050 on Tuesday as oil prices fell below $91. Likely central bank intervention helped the currency rebound from its record low.

The currency of India strengthened on Tuesday, rebounding from an all-time low as a sharp decline in global energy prices and suspected intervention by the central bank helped stabilize the market. This recovery offset a surge in hedging activity by importers who remain concerned about potential energy supply disruptions in the Middle East.
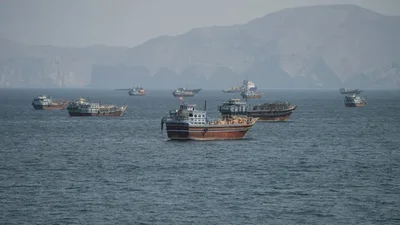
Market sentiment improved globally after the president of the United States suggested that the conflict in the Middle East could be nearing an end. This optimism led to an 8% drop in Brent Crude Oil prices, which fell below $90.8 per barrel after reaching nearly $120 a day earlier. However, the situation remains tense as military officials in Iran warned they would block oil shipments if attacks against them continue.
The rupee finished the day at 91.8050, up 0.57% from its previous close and recovering from its all-time low of 92.3475 per dollar. Traders noted that the Reserve Bank of India likely sold dollars to support the currency from the start of the session. The positive sentiment also lifted Indian equities, with the Nifty 50 index rising nearly 1%.
Dilip Parmar, a foreign exchange research analyst at HDFC Securities, highlighted the impact of energy costs on the currency markets.
"Energy prices remain the key driver for FX markets at the moment."
Despite the day's gains, the cost of hedging against further depreciation has increased, with the rupee's one-month implied volatility hitting 6.4%, its highest level since May 2025. Parmar suggested that the market's directional bias remains focused on the dollar.
"While its difficult to forecast a range at the moment, the directional bias towards buying (USD/INR) on dips will likely persist."