Swiss National Bank Signals Intervention to Curb Rising Franc
The SNB is ready to intervene in currency markets as the franc hits a decade high against the euro. Officials aim to curb appreciation and protect price stability.

The Swiss National Bank (SNB) has announced an increased willingness to intervene in foreign currency markets to counter what it describes as the "excessive" appreciation of the Swiss franc. This move comes as conflict in the Middle East has driven investors toward safe-haven assets, pushing the franc to its highest level against the euro in more than a decade. In early trading on Monday, the EUR/CHF exchange rate fell to 0.9037, its lowest level since the significant currency shift of January 2015.
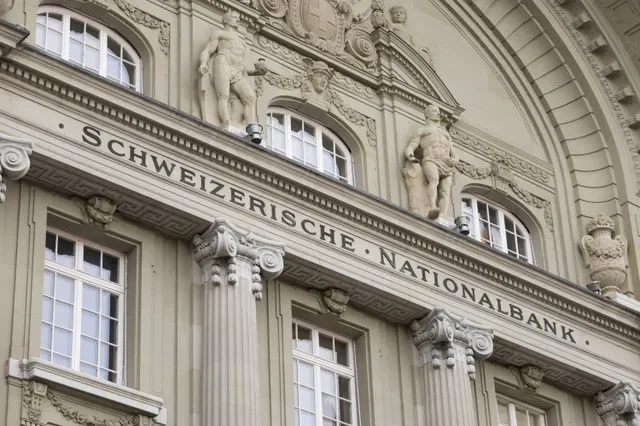
The central bank's rare verbal intervention is intended to check the rise of the franc, which officials fear could push inflation into negative territory and damage the competitiveness of national exporters. The SNB issued a statement clarifying its stance in light of recent global volatility.
In view of international developments, our willingness to intervene in the foreign exchange market has increased.
We are prepared to intervene in the foreign exchange market to counter a rapid and excessive appreciation of the Swiss franc, which jeopardises price stability in Switzerland.
This is the first time the SNB has made such a declaration since 2016, a period when the United Kingdom voted to leave the European Union, causing a similar spike in demand for the franc. Analysts suggest that while the SNB is likely to sell francs to slow the currency's momentum, it is unlikely to push interest rates below the current 0% level.
Alessandro Bee, an economist at UBS, noted that while interventions are expected to take some momentum out of the currency move, the bank is unlikely to defend a specific exchange rate level.
We could expect some interventions by the SNB to slow this movement, but we dont see the SNB defending a certain level and prevent the franc going below that.
Bee further explained that the current situation is driven by geopolitics and risk aversion rather than the structural economic problems seen in previous crises.
That would only be appropriate if there were long-term problems like a slowdown in the global economy or other central banks were cutting rates.
The economist concluded that because the current spike is not a structural issue within the euro zone, the SNB will likely avoid emergency measures unless the global economic situation faces a more permanent downturn.