Senegal Makes Key Debt Payment as Economic Pressure Mounts
Senegal will pay $480 million in debt today despite a $13 billion hidden deficit. Spending cuts and payment delays to other lenders fuel growing civil unrest.

Senegal has announced it possesses sufficient liquidity to meet nearly $500 million in debt obligations due this Friday, though the nation faces mounting fiscal pressure and signs of broader economic distress. The government of President Bassirou Diomaye Faye, which assumed power in April 2024, recently uncovered $13 billion in previously undisclosed debt. This discovery led the International Monetary Fund (IMF) to suspend funding and effectively closed off access to international bond markets, forcing the country to rely on regional financing.
Yvette Babb, a portfolio manager with William Blair, noted that the government remains highly focused on meeting the $480 million payment due on two Eurobonds to maintain its standing with creditors. However, the prioritization of these payments comes at a significant cost to domestic stability and other financial commitments.
\"The authorities remain very committed in portraying their ability to make this payment.\"
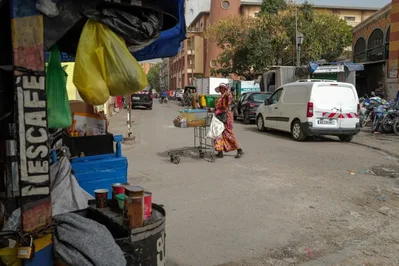
The fiscal crisis has already sparked social unrest. A university student was killed during protests over aid last month, and ongoing strikes by teachers and unions highlight the growing tension. In the construction sector alone, tens of thousands of jobs have been lost. To address the deficit, the government has announced the closure of 19 state agencies, which will result in the loss of 1,000 jobs but is expected to save 55 billion CFA francs.
The $13 billion in hidden debt is unprecedented for a nation under an IMF program. By comparison, the tuna bond scandal in Mozambique involved approximately $2 billion. With debt levels estimated at 132% of economic output, the government is attempting to navigate a path toward sustainability through tax increases and spending cuts, though many analysts remain cautious about the lack of IMF support.
Reports indicate that while Eurobond payments are being prioritized, the government has experienced delays in payments to official lenders, including France, the United Kingdom, Italy, and Spain. While these delays are reportedly within 90-day grace periods, they have drawn the attention of the Paris Club of official lenders.
Future financing needs remain a significant hurdle. Calculations by JPMorgan Chase & Co. suggest that the country requires $9.7 billion for interest and amortization this year, followed by $7.8 billion in 2027 and $8.7 billion in 2028. Chris Celio of ProMeritum Investment Management expressed doubt that short-term regional borrowing and asset sales would provide the necessary long-term stability.
\"I dont think its realistic.\"
The government remains wary of a formal debt restructuring, which Prime Minister Ousmane Sonko has described as a potential disgrace. The administration is mindful of the protracted difficulties faced by other nations, such as the six-year restructuring process in Zambia and the market freeze that occurred in Ghana. Gustavo Medeiros, head of research at Ashmore Group PLC, emphasized the risks inherent in sovereign defaults.
\"Historically, when countries default on their debt, things get really nasty.\"