Analysts remain cautious about the impact of these diplomatic efforts. Suvro Sarkar, energy sector team lead at DBS Bank, noted the discrepancy between market sentiment and physical realities.
While the market is thinking the worst is over and factoring in further rounds of peace talks between the U.S. and Iran in the coming days, there is more hope than actual developments at this point.
Physical oil prices continue to trade at significant premiums over futures, reflecting a scramble for available supply. Refiners in Europe and Asia are seeking alternatives to Gulf crude, driving up prices for North Sea and U.S. Gulf Coast grades. For instance, WTI Midland for delivery to Rotterdam recently hit a record premium of $22.80 per barrel over European benchmarks.
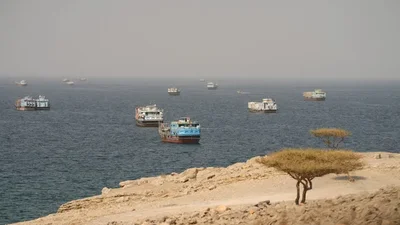
Despite a temporary ceasefire, maritime traffic through the Strait of Hormuz remains a fraction of its pre-war levels. Reports indicate that a U.S. destroyer intercepted two tankers attempting to depart from Iranian waters on Tuesday. The Schork Group emphasized the disconnect between political rhetoric and the situation on the ground.
While diplomatic headlines suggest the possibility of renewed U.S.-Iran talks and even a temporary easing of transit restrictions, the physical reality remains fragmented.
Supply constraints may tighten further as the American administration signaled it would not renew sanctions waivers for Iranian oil currently at sea. Similarly, a waiver regarding oil from Russia was allowed to expire over the weekend. These developments are being monitored closely by analysts in Japan and Singapore as they assess the impact on global flows.
Investors are now awaiting official inventory data from the Energy Information Administration. While early figures from the American Petroleum Institute suggested a rise in crude stockpiles, market participants are looking for confirmation on whether distillate and gasoline inventories have continued to decline.