Stocks Fall and Oil Prices Rise Amid Middle East Conflict
Global stocks fell on Thursday as rising oil prices and bond yields sparked concerns about stagflation. Markets are now awaiting Friday's U.S. payrolls report.

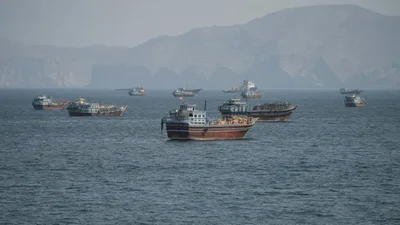
Global financial markets retreated on Thursday as an intensifying conflict in the Middle East fueled concerns over energy supplies and the potential for stagflation. While equities in Japan rose 2% and South Korea surged 10% during the Asian session, the momentum failed to carry over to the West. Indices in the United States and Europe slid into the red, with the Brazil market dropping 2.5% and Mexico falling 3%. The Nasdaq showed relative resilience, closing down only 0.3%, while the small-cap Russell 2000 index fell 2%. Within the equity markets, sector performance was broadly negative as eight of the eleven S&P 500 sectors declined. Industrials, consumer staples, healthcare, and materials all fell by 2% or more. Among individual stocks, Caterpillar Inc. and The Goldman Sachs Group, Inc. both saw their shares drop 3.5%. In contrast, International Business Machines Corporation managed to gain 2.5% despite the broader market downturn. The escalation follows reports of strikes involving Iran and Israel, which have sent shockwaves through the commodities sector. Brent Crude Oil jumped 5% on the day, contributing to a weekly surge of nearly 20%. This represents the most significant weekly increase for oil prices since February 2022. Conversely, Gold fell 1.5% as investors adjusted to a strengthening dollar and rising bond yields. In the currency markets, the dollar posted gains against most major and emerging market peers. The Australia dollar was the biggest decliner among G10 currencies, falling 1%. Emerging market currencies were hit harder, with the South Africa rand and the Chile peso both losing approximately 2%. Fixed income markets also reflected growing anxiety, with bond yields in the United Kingdom rising 10 basis points. In Germany, the two-year Schatz yield has climbed 25 basis points this week, marking its most significant move in three years. Market participants are also monitoring political developments in China, where parliament has introduced a new economic and political blueprint. Looking ahead to Friday, the focus will shift toward labor market data in the U.S. and PMIs in Canada. Other key indicators expected include inflation figures from South Korea and industrial production data from Europe. Central banks, including the European Central Bank and the Reserve Bank of Australia, remain under scrutiny as they navigate supply-side shocks and shifting inflation expectations.