Energy markets are bracing for a review of production plans by the OPEC+ group, which includes Russia. Although Brent Crude Oil has reached its highest levels since last July, rising 17% in 2026, the International Energy Agency anticipates a significant surplus. This forecast is underpinned by expectations that additional supply will originate from non-member nations, specifically Canada, Brazil, Argentina, and Guyana. Higher energy costs are generally expected to constrain demand despite the current price rally.
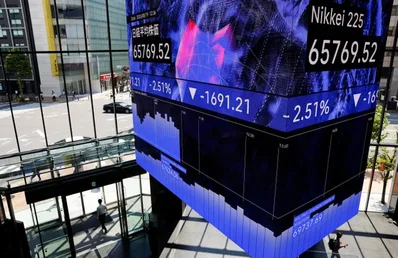
Asia’s primary economies are also in the spotlight. China is set to convene its National People's Congress to establish growth, inflation, and spending targets for the coming year. Meanwhile, Japan will conduct government bond auctions to gauge demand following a period of historic yield volatility. Global debt markets remain sensitive to the fiscal stimulus plans of Prime Minister Sanae Takaichi and recent dovish nominations to the Bank of Japan board.
Geopolitical instability continues to influence asset valuations. Ongoing friction between the U.S. and Iran has supported the price of Gold, which continues to edge higher amid concerns over regional stability and the potential collapse of conflict-averting talks. Investors are also monitoring the potential for new trade tariffs, which could redefine traditional relationships between asset classes and the dollar as safe-haven definitions remain in flux.
In Mexico, political developments are expected to influence the USD/MXN exchange rate as Congress debates a bill to significantly reduce electoral spending. The proposed reforms, which include caps on political financing and regulations for AI-generated content, face a challenging path to approval. This legislative activity occurs as President Claudia Sheinbaum prepares for critical USMCA trade renegotiations and the country manages the security fallout from the recent killing of a major drug lord.