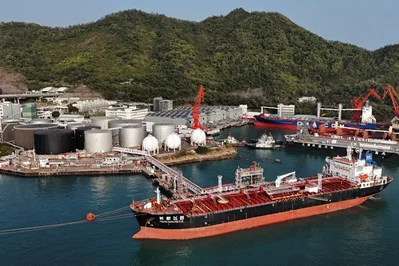
Refinery activity remained strong, with capacity utilization reaching 71.3% in January and 73.2% in February, both marking improvements over the previous year. Emma Li, an analyst at Vortexa, noted that the surge was supported by both high throughput and a significant increase in stockpiling.
Higher crude imports were due to stronger refining throughput in the first two months of 2026, as well as stockpiling, with inventories rising by about 25 million barrels.
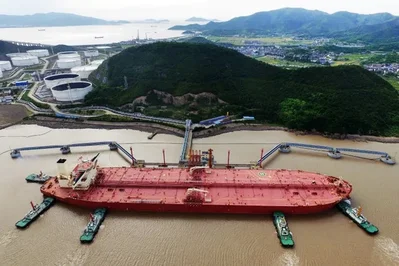
According to Kpler, seaborne imports rose to 10.88 million bpd in January and 11.47 million bpd in February. Shipments from Russia were particularly strong, nearly doubling from the previous year. This increase was facilitated by a shift in regional demand, as India scaled back its purchases, leaving more discounted Russian barrels available for Chinese refiners.
This was mainly because India reduced its purchases, leaving more cargoes available to China at lower prices.
Additionally, imports from Iran saw a modest increase, serving as a cost-effective alternative to crude from Venezuela. These market dynamics persist even as global markets monitor benchmarks like Brent Crude Oil for broader pricing trends. Beyond crude, China's exports of refined products rose 12.7% to 8.13 million tons, while natural gas imports saw a slight decline of 1.1% to 20.02 million tons.