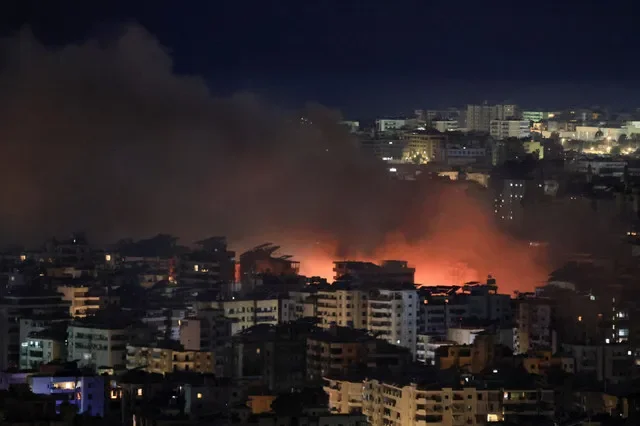
The conflict continues to exert significant pressure on global logistics, impacting everything from international shipping lanes to commercial aviation. Political rhetoric has also intensified, with U.S. President Donald Trump indicating a desire for involvement in determining the future leadership of Iran. These developments have kept energy markets on edge, with crude prices tracking toward their most substantial weekly increase since the invasion of Ukraine by Russia in early 2022.
In Asia, equities suffered their worst weekly performance in six years as investors grappled with the dual threats of war and persistent inflation. Hawkish sentiment is growing, with market participants pricing in more aggressive interest rate trajectories from major central banks, subsequently driving bond yields higher.
Amid the geopolitical noise, the focus remains on the upcoming February nonfarm payrolls report. The world's largest economy is projected to have added 59,000 jobs in February, a sharp deceleration from January's 130,000 gain. The unemployment rate is projected to hold steady at 4.3%. While analysts are watching for early signs of labor displacement related to artificial intelligence, the primary concern remains whether the data will signal a broader economic slowdown or a problematic rise in joblessness. Key developments that could influence markets on Friday include speeches from Federal Reserve officials Daly, Paulson, Collins, and Hammack.